Energy Costs: from volatility management to strategic advantage
Learn how to turn energy cost volatility into a strategic advantage through effective risk management, greater financial predictability, and enhanced business competitiveness.
19 Oct 2026 6 min read
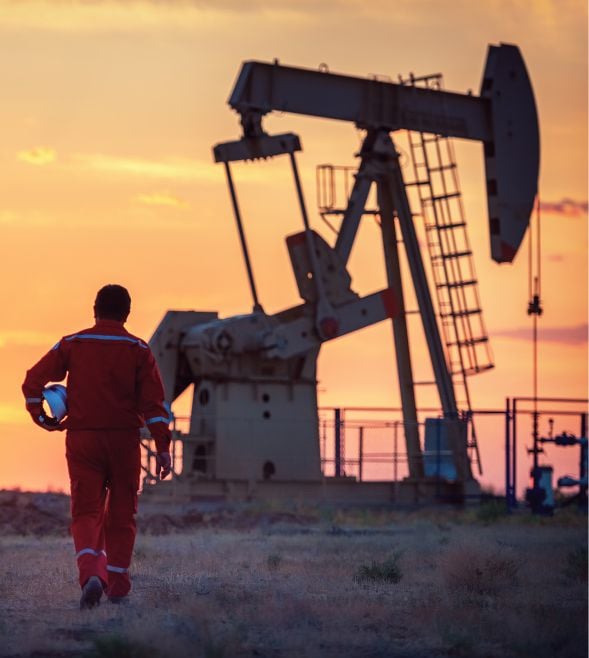
The conflict in the Middle East that began in February this year has brought the debate around security of energy supply and the vulnerability of a system that depends heavily on geopolitically sensitive regions to the forefront. “In this context, importing countries are seeking to diversify their suppliers,” comments Gabriel Righini, Audit Lead Partner and Energy and Natural Resources industry spokesperson at Grant Thornton Argentina. “And Latin America will play a key role in supplying energy from countries outside the Organization of the Petroleum Exporting Countries (OPEC).”
Attention is focused on the Neuquén Basin, especially on the Vaca Muerta formation, which holds the world’s 4th-largest unconventional oil reserves and 2nd-largest unconventional gas reserves. This sedimentary formation, deposited in a Jurassic-age sea, was discovered in 1931, when American geologist Charles Edwin Weaver identified and named the geological formation in the Sierra de Vaca Muerta, within the Neuquén Basin.
For decades, it was studied as an organic-rich source rock, but its energy potential could not be developed due to the technological limitations of the time. It was only with advances in horizontal drilling and hydraulic fracturing that its large-scale development became feasible. In 2011, the potential of the Vaca Muerta formation’s unconventional resources was confirmed, and in 2013 the first projects began, turning it into Latin America’s leading shale hub.
 “In less than 15 years, Vaca Muerta has progressed from exploratory wells to a production model involving multiple pads and operations that, in July this year, accounted for 70% of national production, setting a new all-time high,” highlights Righini. “The increase in productivity can be explained by the adoption of new tools, optimisation of the different stages of extraction, accumulated know-how and increased investment.”
Argentina ranks among the countries with the largest technically recoverable unconventional (shale) hydrocarbon resources. Vaca Muerta’s current production represents only a fraction of the formation’s theoretical capacity, and the Régimen de Incentivo a las Grandes Inversiones (RIGI - Large Investment Incentive Scheme) has become one of the main catalysts for scaling up production and export infrastructure. “The Ministry of Economy has currently approved seven Vaca Muerta-related projects, totalling US$27.486 billion in Neuquén, Río Negro, La Pampa and Buenos Aires,” comments Estanislao de León, Audit Partner and Energy and Natural Resources industry spokesperson at Grant Thornton Argentina.
The Cámara de Exploración y Producción de Hidrocarburos (CEPH - Argentine Chamber of Hydrocarbon Exploration and Production) expects RIGI to enable production to increase to 1.7 million barrels of oil per day and 300 million cubic metres of gas per day by 2035, compared with 500,000 barrels and 120 million m³ prior to the regime.
Source: Ministry of Economy – Data as of 8 October.
“RIGI unlocked one of the main bottlenecks affecting Vaca Muerta,” adds de León. “Argentina has one of the lowest gas costs in the world, but midstream constraints affect the basin’s capacity, growth and value. Three of the approved projects include oil pipelines, one of which will supply the floating liquefaction units that will be installed in the San Matías Gulf, also as a RIGI project. In addition, one project will install new compressor plants to increase the transport capacity of the Perito Francisco Pascasio Moreno gas pipeline.”
For many, the comparison with the Permian is inevitable. This US basin was the main driving force behind the shale revolution and turned the United States into one of the world’s largest hydrocarbon producers. Its growth was underpinned by a combination of favourable geology, abundant financing, specialised service companies, available infrastructure and direct access to refining centres and export terminals.
In strictly production terms, some areas of Vaca Muerta are already delivering results comparable with the best-performing areas of the Permian. “The difference between the two lies above ground,” comments de León. “Access to financing and technological, logistical and supply capabilities in the US basin are more developed than in Argentina. However, this ecosystem is being built in Vaca Muerta, while future constraints, such as workforce availability, are also being addressed.”
The seven projects approved under RIGI will generate demand for 28,993 direct and indirect jobs. In anticipation of future demand for skilled workers, the industry’s leading operating and service companies created the Vaca Muerta Institute to develop and train the technical profiles needed to ensure operational excellence in the upstream sector. Another constraint faced by the Permian during its development was logistics costs, an issue that Vaca Muerta is currently facing, particularly in relation to the sand used for hydraulic fracturing. In this regard, the country needs to develop railway infrastructure or promote greater use of the Paraná Waterway to reduce costs and shorten transport times.
Vaca Muerta is currently undergoing its greatest expansion since commercial development began. In May 2026, Argentina’s oil production reached 903,700 barrels per day (bpd), with 70% coming from Vaca Muerta. In July, the formation set a new production record of 643.1 thousand bpd and 96.5 million m³/d of gas.
The Bolsa de Comercio de Rosario (BCR - Rosario Board of Trade) reported that fuel and energy exports during the first half of the year reached US$8.118 billion, in a context of improved prices and higher oil production. The Industrial Production Index (IPI) published by INDEC recorded a 14.4% year-on-year increase in national crude oil extraction in August 2026, reaching 4,606,200 m³ per month, driven by a 26.9% year-on-year increase in unconventional oil production to 3,278,600 m³. The Instituto Argentino del Petróleo y del Gas (IAPG - Argentine Oil and Gas Institute) reported in its August monthly report that 79.7% of oil and 76.6% of natural gas were produced in the Neuquén Basin.
Over the past six years, the main destinations for Vaca Muerta production have been the United States, Chile, Brazil, Australia and Peru. In 2025, the United States, Chile and Australia were the main trading partners, while so far in 2026 the United States leads the ranking, followed by Chile and Thailand.
“Vaca Muerta will not replace the Middle East, nor will it achieve the Permian’s accumulated scale in the short term. Its opportunity lies in becoming an additional, competitive and geographically diversified source of oil and gas,” concludes Righini.
“The formation has the resource, the technical expertise and an upward productivity curve. The next leap forward will depend on factors above ground,” adds de León. “If infrastructure and investment conditions advance at the same pace as production, Vaca Muerta will become one of the main drivers of global energy growth.”
Learn how to turn energy cost volatility into a strategic advantage through effective risk management, greater financial predictability, and enhanced business competitiveness.



The IASB issued a new standard on accounting for companies subject to rate regulation: the IFRS 20 ‘Regulatory Assets and Regulatory Liabilities’.
In 2010, the National Congress enacted Law No. 26,639 on Minimum Standards for the Preservation of Glaciers and the Periglacial Environment. Sixteen years later, its amendment was approved.