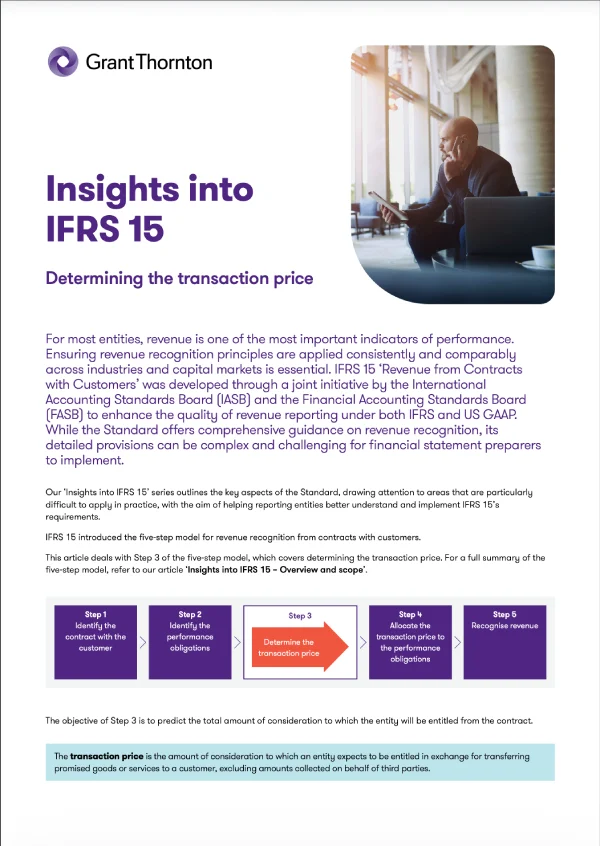
IFRS 15: Principal versus agent considerations
AuditThis article deals with the principal versus agent considerations of IFRS 15.
14 Sep 2026 1 min read
IFRS 15 ‘Revenue from Contracts with Customers’ was jointly developed by the International Accounting Standards Board (IASB) and the Financial Accounting Standards Board (FASB) to align revenue reporting practices under IFRS and US GAAP. The objective of the standard is not to alter the definition of revenue, but to improve comparability by establishing a clear framework for recognising and measuring revenue.
Our ‘Insights into IFRS 15’ series summarises the key areas of the Standard, highlighting some areas that are challenging to apply in practice, to assist reporting entities in understanding how to apply IFRS 15’s requirements.
IFRS 15 introduced the five-step model for revenue recognition and applies specifically to contracts with customers. This article deals with Step 3 of the five-step model, which covers determining the transaction price.
We hope you find the information in this article helpful in giving you some insight into IFRS 15. If you would like to discuss any of the points raised, please contact us.
This article deals with the principal versus agent considerations of IFRS 15.
The objective of IFRS 15 is not to alter the definition of revenue, but to improve comparability by establishing a clear framework for recognising and measuring revenue.
Read the second article in new Insights into IFRS 15 series – ‘Step 1: Identifying a contract with a customer.
First article in new Insights into IFRS 15 series released – ‘Overview and scope’